What Fintech Really Is and How It Is Quietly Rewiring the Way Money Moves
The word fintech gets attached to almost anything involving money and a screen, which makes it easy to dismiss as marketing. Yet the underlying shift is real and consequential. Financial technology describes the software, data, and infrastructure that are steadily unbundling traditional banking and rebuilding it as programmable services. For business leaders, understanding fintech is no longer optional, because it increasingly determines how quickly a company can accept payments, access capital, and manage cash.
Defining a Slippery Term
At its simplest, fintech is the application of technology to financial services. That definition is broad because the category is broad. It spans consumer payment apps, business lending platforms, digital-only banks, investment tools, insurance software, and the behind-the-scenes plumbing that connects them all.
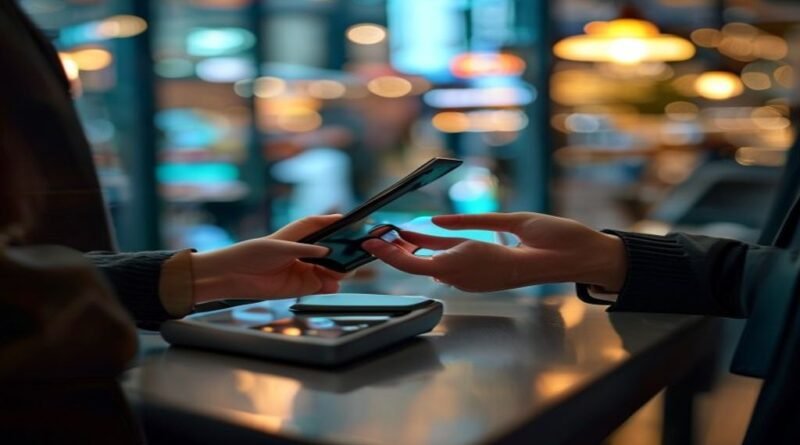
What unites these efforts is a common ambition: to take processes that were slow, paper-based, and locked inside institutions, and turn them into fast, digital, and often self-service experiences. A small merchant that once waited weeks for a bank to approve a card-processing account can now start accepting payments in an afternoon. A shopper who once carried cash can pay with a tap. These conveniences rest on layers of technology that most users never see.
The Building Blocks
It helps to think about fintech in a few functional categories rather than as a single industry:
- Payments. The largest and most mature area, covering everything from point-of-sale terminals to online checkout and cross-border transfers.
- Lending and credit. Platforms that use data to assess risk and disburse loans faster than traditional underwriting allows.
- Banking and accounts. Digital-first providers that offer accounts, cards, and cash management, often aimed at consumers or small businesses underserved by legacy banks.
- Wealth and investing. Tools that lower the cost and complexity of investing, from automated portfolios to fractional share trading.
- Infrastructure. The connective tissue, including data-sharing systems and application programming interfaces, that lets these services talk to one another and to banks.
That last category, infrastructure, is where much of the quiet revolution is happening. Application programming interfaces, or APIs, allow one company to embed financial functions into its own product without becoming a bank itself. A software firm can offer its customers a branded payment card or instant payouts by plugging into a provider that handles the regulated heavy lifting.
Embedded Finance and the Blurring of Lines
This capability has given rise to what the industry calls embedded finance: financial services delivered inside non-financial products. A ride-hailing app that pays drivers instantly, an e-commerce platform that offers sellers working capital, a software tool that lets users pay invoices without leaving the dashboard, all are examples. The financial service becomes a feature rather than a destination.
The most important fintech companies of the next decade may be ones customers never think of as financial at all, because the money simply moves in the background of something else they are doing.
For businesses, embedded finance changes the competitive landscape. Any company with a large, engaged user base can potentially offer financial services, and those services can become significant revenue streams. It also raises the bar for customer experience, because users increasingly expect money to move as smoothly as a message.
Why Incumbents and Startups Are Converging
Early narratives framed fintech as scrappy startups disrupting stodgy banks. The reality has matured into something more collaborative. Startups discovered that regulation, trust, and capital requirements are formidable barriers. Established banks discovered that modern software and design are hard to build from scratch. The result is a web of partnerships in which technology firms provide the experience and regulated institutions provide the license and balance sheet.
This convergence carries a lesson for any leader evaluating financial technology. The winning question is rarely startup versus bank. It is which combination of providers delivers the capability you need with the reliability and compliance your customers deserve.
What Leaders Should Watch
Several themes will shape how money moves in the coming years. Real-time payment systems are reducing the delay between a transaction and settled funds, which improves cash flow and changes how businesses manage liquidity. Data-sharing frameworks are giving customers more control over their financial information, enabling new services built on that data. And regulators worldwide are working to keep pace, balancing innovation against consumer protection and financial stability.
For a business, the practical implications are concrete. Payment costs and speed affect margins and customer satisfaction. Access to embedded lending can smooth cash flow. The ability to integrate financial data can unlock better forecasting. None of this requires becoming a technologist, but it does require treating financial infrastructure as a strategic choice rather than an afterthought.
Fintech, in the end, is less about flashy apps than about a fundamental rewiring of financial plumbing. Money is becoming faster, more programmable, and more deeply woven into everyday software. The companies that understand this shift, and choose their financial infrastructure deliberately, will hold a quiet but durable advantage.
